Beyond the Mortgage: The Real Cost of Owning Your Dream Home
Beyond the Mortgage: The Real Cost of Owning Your Dream Home
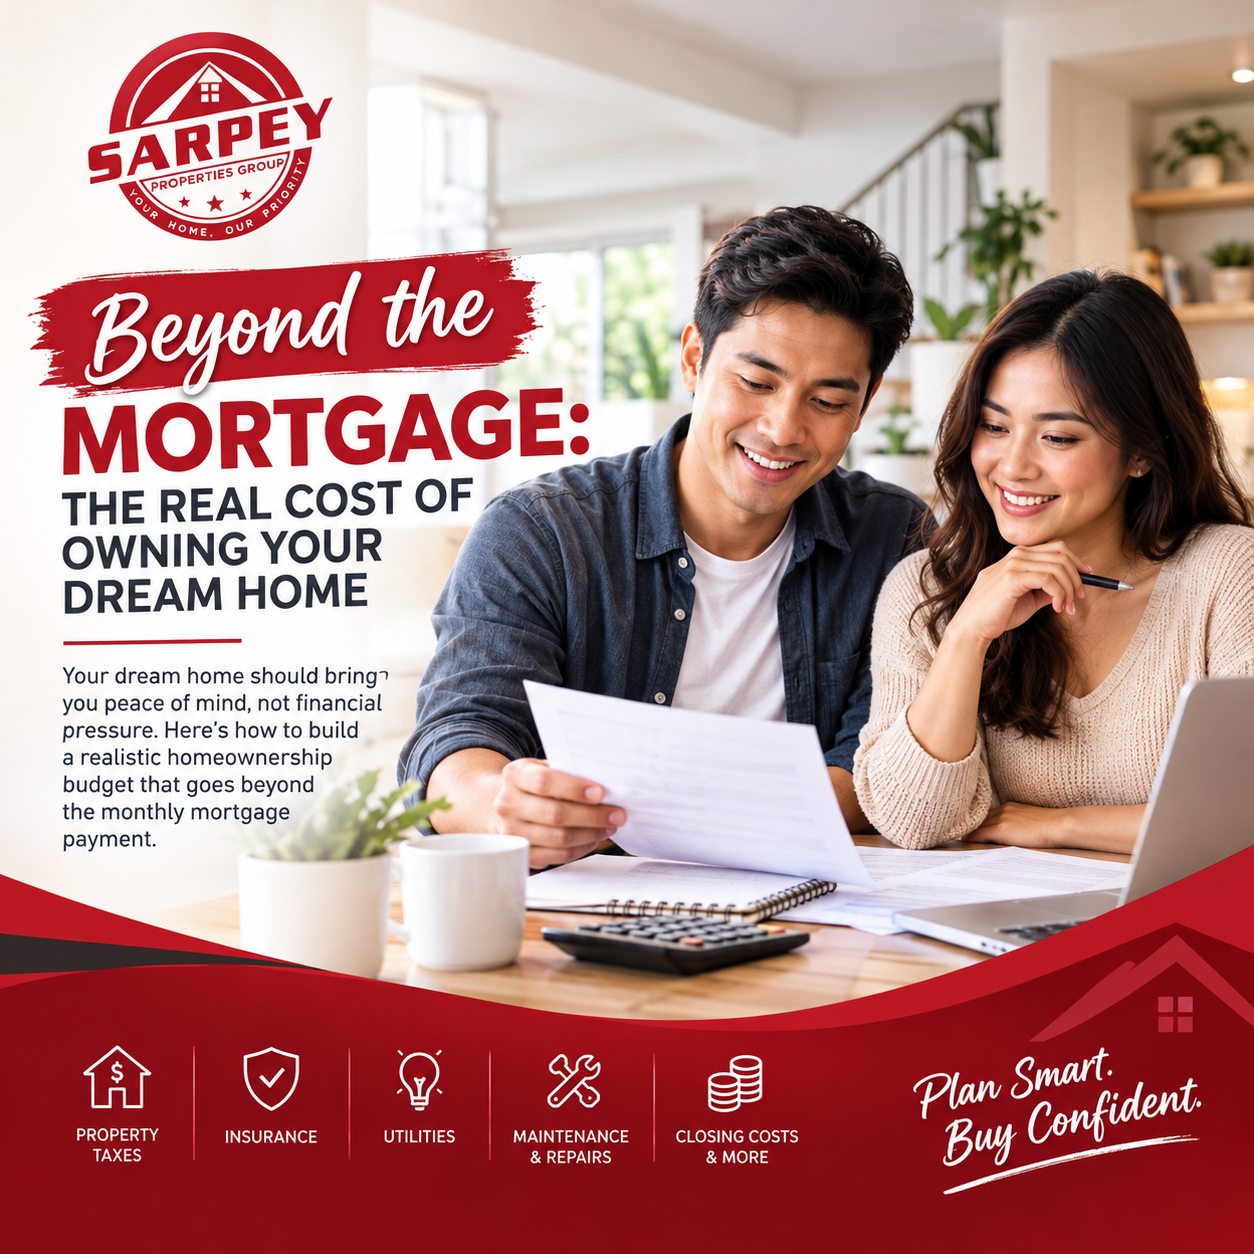
Your dream home should bring you peace of mind, not financial pressure. Here’s how to build a realistic homeownership budget that goes beyond the monthly mortgage payment.
Imagine stepping through the front door of your new home for the first time. The keys are in your hand, the rooms are waiting to be filled, and you can finally picture the life you have been working toward. Perhaps you see family dinners in the kitchen, quiet mornings in the living room, or weekends spent creating memories in a place that is truly yours.
It is an exciting moment—and for many people, a lifelong dream come true.
But a few months after moving in, reality begins to settle. The electricity bill arrives. The water bill follows. Something needs repairing, the insurance payment is due, and suddenly, the monthly expenses are higher than expected.
Sound familiar?
This is one of the most overlooked aspects of buying a home: being able to afford the mortgage does not automatically mean you can comfortably afford the home.
The good news? With the right preparation, a realistic budget, and guidance from knowledgeable real estate professionals, you can make a more confident decision before signing on the dotted line.
At Sarpey Properties Group, we believe that finding the right property should go hand in hand with understanding what it takes to own it. Because the goal is not simply to help you find a house. It is to help you make a homeownership decision that fits your life, your priorities, and your financial future.
The Mortgage Is Only the Beginning
When buyers start searching for a home, the conversation often begins with one question: How much can I afford to borrow?
It is an important question, but it is only part of the picture.
A mortgage lender evaluates your financial situation to determine how much you may qualify to borrow. That assessment can be useful, but your personal comfort level may be different from the maximum amount a lender is willing to approve.
Think about it this way. Two buyers could qualify for the same mortgage, yet have very different financial realities. One may have substantial savings, minimal debt, and stable household expenses. The other may be managing student loans, childcare costs, family obligations, or plans to start a business.
The same monthly mortgage payment could feel manageable for one buyer and overwhelming for the other.
That is why your homebuying budget should begin with a broader question: How much can I comfortably spend on housing while still enjoying the life I want to live?
Your answer should account for more than your income. It should reflect your everyday expenses, financial commitments, savings goals, and the unexpected costs that life inevitably brings.
A home should be part of a healthy financial plan—not the reason you have to abandon every other goal.
The Costs You May Not See Coming
One of the easiest mistakes to make when shopping for a property is focusing so closely on the purchase price that everything else fades into the background.
You find a home you love. The monthly mortgage estimate looks reasonable. You start imagining where the sofa will go and what color to paint the spare bedroom. Before long, you are emotionally invested.
But before you commit, take a step back and look at the complete cost of ownership.
Property taxes and insurance
Depending on where you buy, property taxes can represent a significant recurring expense. Property tax assessments and rates may change over time, so it is worth understanding the current amount and how future changes could affect your budget.
Homeowners insurance is another expense to investigate before closing. Coverage, premiums, deductibles, and exclusions can vary depending on the property and location. Some homes may also require additional coverage for particular risks.
If you are purchasing a condominium or a property within a homeowners association, you may have recurring association fees as well.
These costs can change the true monthly expense of a property considerably. That is why comparing homes based on the mortgage alone can give you an incomplete picture.
Utilities and everyday living expenses
A larger home may offer more space, but it can also mean higher heating, cooling, water, and electricity bills.
The home's age, insulation, appliances, climate, and energy efficiency can all influence operating costs. A property with a swimming pool, extensive landscaping, or additional amenities may introduce further expenses.
Before buying, ask whether you can obtain historical utility bills or a reasonable estimate of typical operating costs. Consider the practical realities of maintaining the property, not just how attractive it looks during a showing.
And remember that you still need money for groceries, transportation, healthcare, family activities, and everything else that makes your household function.
Your budget should leave room for living—not just for owning.
Maintenance, repairs, and the unexpected
Every home needs attention eventually. A roof may need replacing, an appliance may stop working, plumbing may require repairs, or an air-conditioning system may need servicing at the worst possible time.
Even a newly built home is not completely free from ongoing costs.
The important thing is to plan for maintenance before something breaks. Set aside money regularly in a dedicated home maintenance fund, adjusting the amount according to the property's age, condition, size, and features.
There is no single reserve amount that works for every home. A professional inspection and a realistic assessment of the property's condition can help you estimate likely expenses more accurately.
This is also where an emergency fund matters. Your home maintenance savings can cover foreseeable upkeep, while a broader emergency fund can help protect you against unexpected income disruptions or other major expenses.
Financial preparation is not about predicting every problem. It is about making sure that one unexpected problem does not become a financial crisis.
Don't Forget the Cost of Getting Into Your Home
The expenses of homeownership can begin long before your first mortgage payment.
Depending on your transaction and location, you may need to budget for a down payment, loan origination charges, appraisal fees, inspections, title or legal services, recording fees, prepaid taxes, insurance, and other closing costs.
The specific expenses and who pays them will depend on the property, the financing arrangement, and local practices.
Then comes moving day.
You may need to hire movers, arrange transportation, purchase furniture, install window coverings, replace locks, connect utilities, or make minor improvements before settling in. Even seemingly small purchases can add up when you are furnishing an entire home.
This is why your savings plan should separate the money needed to purchase the property from the money needed to move in and live comfortably afterward.
It can be tempting to put every available dollar toward the down payment. But arriving at your new home with almost nothing left in savings can leave you vulnerable when the first unexpected expense appears.
A better approach is to establish a realistic cash requirement for the entire move, including the funds you want to preserve for emergencies.
The objective is not merely to get the keys. It is to start the next chapter of your life on solid financial footing.
Build a Budget Around Your Real Life
So, how do you turn all these expenses into a practical homeownership budget?
Start with your actual monthly take-home income—the money that reaches your bank account after taxes and payroll deductions. If your income varies, use a conservative estimate rather than assuming every month will be your best month.
Next, account for your existing financial commitments. Include debt payments, groceries, transportation, healthcare, childcare, subscriptions, family support, and regular savings contributions.
Then calculate your complete housing cost. Include the expected mortgage payment, property taxes, homeowners insurance, association fees where applicable, utilities, and a monthly allocation for maintenance.
Finally, look at what remains.
Does the budget still allow you to save for retirement, handle emergencies, pay down other debts, and enjoy a reasonable quality of life? Could you manage if utilities increased, insurance premiums rose, or an appliance needed replacing?
If the numbers leave you feeling squeezed before you have even moved in, that is useful information. It may mean you need to consider a lower purchase price, increase your savings, reduce other obligations, or explore a different type of property.
There is no shame in adjusting your expectations. In fact, doing so before buying can be one of the smartest financial decisions you make.
A home that fits your budget today—and leaves room for tomorrow—is often a better choice than a more expensive property that stretches you to your limits.
Give Your Future Self Some Breathing Room
A realistic homeownership budget should not only account for what you spend today. It should also consider what your life might look like in the years ahead.
Perhaps you are planning to grow your family, change careers, return to school, start a business, or prepare for retirement. Maybe you want to travel more, support aging parents, or build an investment portfolio.
Your housing decision can influence how easily you pursue those goals.
That does not mean you must predict the future perfectly. It means leaving enough flexibility in your finances to respond when life changes.
Try testing your proposed budget against a few less comfortable scenarios. What if your monthly expenses increase? What if you need to replace a major appliance? What if your household income temporarily falls?
If your plan only works under perfect conditions, it may need another look.
Keeping an emergency reserve, avoiding unnecessary debt, and reviewing your budget periodically can help you remain financially resilient after the excitement of buying a home has passed.
Remember, the best home is not necessarily the largest or most impressive one you can qualify for. It is the one that supports your lifestyle without compromising your financial security.
Choose a Home With Your Eyes Open
Of course, numbers are only one part of the decision.
You should also consider location, commute times, access to schools and essential services, neighborhood conditions, property condition, future plans, and the features that genuinely matter to your household.
A less expensive home farther from work, for example, may come with higher transportation costs. A larger property may require more maintenance. A condominium may offer convenience but involve association fees and rules that deserve careful review.
This is why comparing properties requires more than comparing listing prices.
Take the time to understand the full picture. Ask questions, review the available documents, arrange appropriate inspections, and consult qualified financial, lending, tax, or legal professionals when needed.
A trusted real estate professional can help you evaluate property options, understand transaction considerations, and identify questions worth investigating before you commit.
At Sarpey Properties Group, this is the kind of thoughtful approach buyers should look for in their real estate journey: one that encourages informed decisions rather than rushed commitments. You can explore available properties and learn more about the company at www.sarpeypropertiesgroup.com.
The right guidance cannot eliminate every uncertainty, but it can help you approach the process with better information and a clearer understanding of your options.
A Dream Home Should Feel Like a Win Long After Closing
There is something special about owning a home. It can provide stability, a place to build memories, and an opportunity to create a space that reflects who you are.
But the real reward is not simply the moment you receive the keys. It is the experience of living there month after month, knowing you can meet your obligations, handle life's surprises, and still make progress toward the future you envision.
That is what makes a realistic homeownership budget so important.
Look beyond the mortgage. Account for taxes, insurance, utilities, maintenance, closing costs, and the everyday expenses that continue long after moving day. Protect your savings, leave room for emergencies, and be honest about what you can comfortably afford.
And when you begin exploring properties, seek guidance from professionals who understand that a home purchase is more than a transaction. It is a significant financial and personal decision.
At Sarpey Properties Group, your home search can begin with the right questions, a clearer understanding of your priorities, and a thoughtful look at the options available to you.
Ready to take the next step toward homeownership?
Visit www.sarpeypropertiesgroup.com to explore properties and connect with a real estate professional who can help you move forward with greater confidence.
Your dream home should be a source of comfort, opportunity, and lasting memories—not a constant source of financial stress.
Plan beyond the mortgage. Buy with confidence. Build a future you can afford.
Categories
- All Blogs (40)
- 2026 Housing Market (2)
- Buyer Education (2)
- Buyer Resources (9)
- buyer strategy (3)
- Buyer tips (5)
- buying power (2)
- buying power, (1)
- Buying Tips (3)
- Client success stories (2)
- delaware home (1)
- Delaware Real Estate (26)
- delaware realtor (2)
- energy efficiency (1)
- First time home buyer (10)
- home affordability (2)
- Home buyer (9)
- Home buying (19)
- Home Buying & Selling (2)
- home buying and selling (20)
- home buying tips (8)
- home financing (3)
- home improvement (1)
- home inspections (2)
- home owner tips (2)
- home ownership (4)
- home seller tips (2)
- home sellers (2)
- home selling (10)
- home selling tips (11)
- home staging (3)
- home valuation (6)
- Homeownership (9)
- Homeownership Buyer Education (1)
- house (6)
- house buying guide (6)
- house hunting (6)
- housing market forecast (2)
- housing market trend (4)
- interest (4)
- interested rates (3)
- Landlord Tips (1)
- Lifestyle & Community Guides (1)
- Location & Lifestyle (1)
- market (7)
- market, (1)
- maryland home (2)
- Maryland Real Estate (28)
- maryland realtor (3)
- mortgage (5)
- mortgage and financing (6)
- mortgage approval (2)
- mortgage loans (1)
- open house tips (2)
- pennsylvania home (2)
- Pennsylvania Real Estate (27)
- pennsylvania realtor (2)
- property (1)
- Real Estate Advice (19)
- Real Estate Investment (1)
- Real Estate Market Insights (8)
- real estate market trends (2)
- real estate marketing (7)
- real estate negotiation (3)
- Real Estate Planning (1)
- real estate professionals (8)
- real estate selling tips (4)
- Real estate tips (14)
- Real estate, (14)
- Relocation & Moving (1)
- rental properties (1)
- residential real estate (3)
- Sarpey (10)
- Sarpey Properties Group (11)
- seller preparation (1)
- seller resources (7)
- seller strategies (2)
- seller strategy (1)
- Selling vs Renting (1)
- tax (3)
- Tri-State Real Estate (3)
- wealth building (3)
Recent Posts

"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "