How Buyers Can Create a Realistic Homeownership Budget Beyond the Mortgage
How Buyers Can Create a Realistic Homeownership Budget Beyond the Mortgage
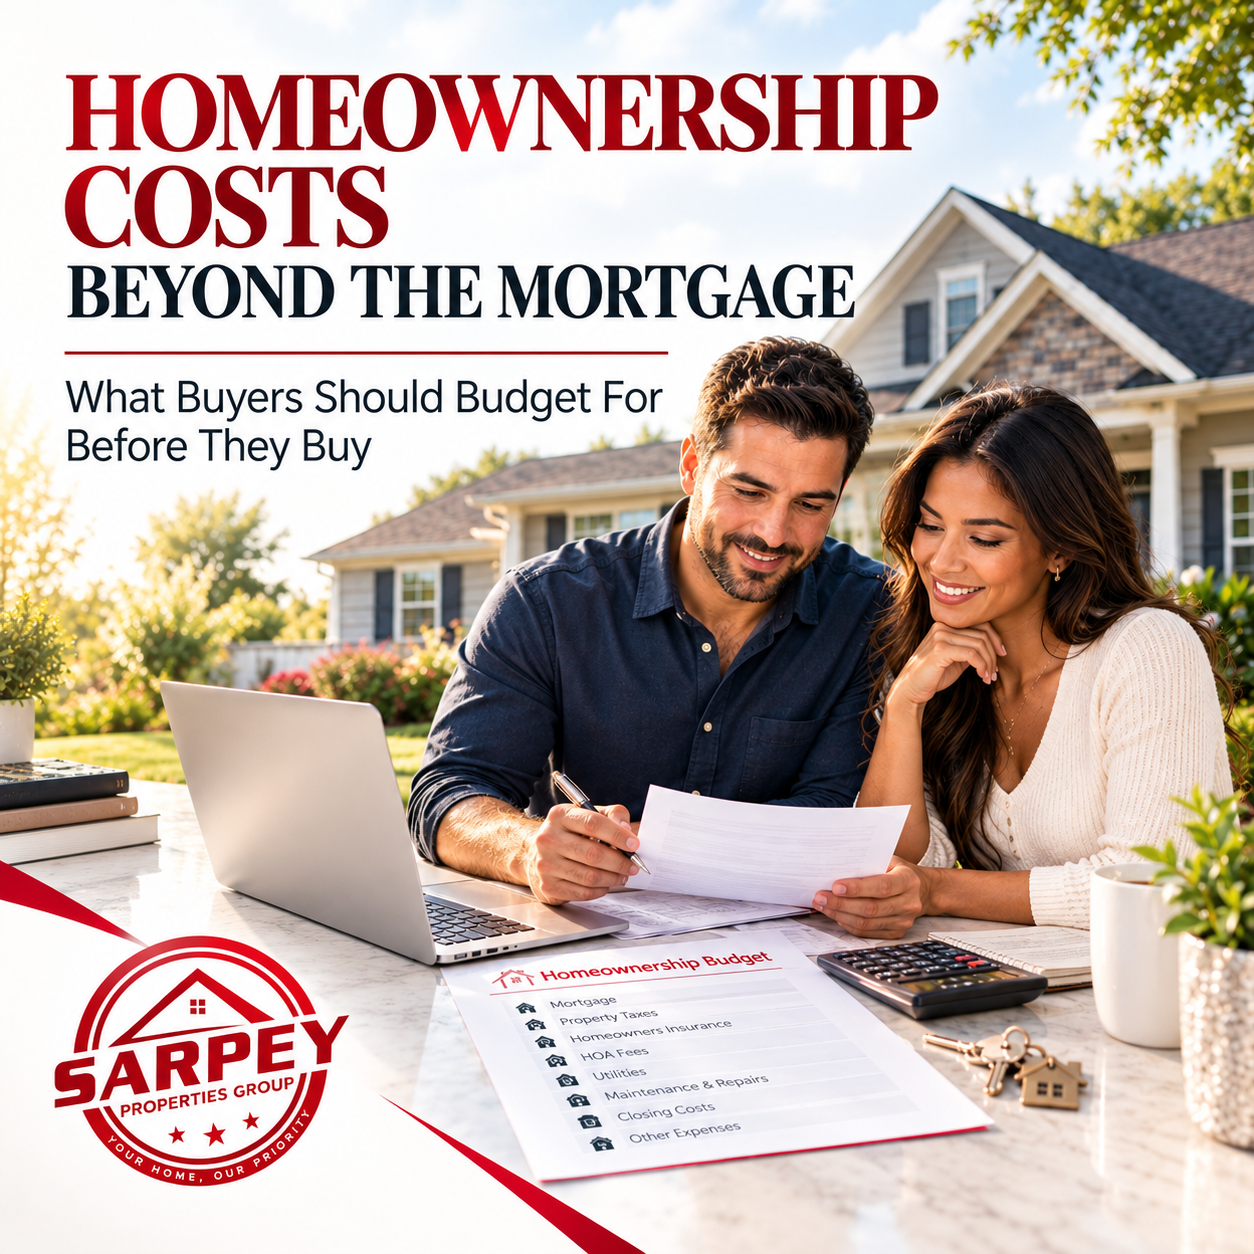
Think you can afford the house because you can afford the mortgage? Think again.
One of the biggest mistakes homebuyers make is focusing almost entirely on the monthly mortgage payment.
Your mortgage is certainly one of the largest expenses of owning a home—but it is only one piece of the homeownership budget.
Property taxes, homeowners insurance, utilities, maintenance, repairs, HOA fees, closing costs, and even the occasional unexpected expense can significantly change what a home actually costs each month.
Before you fall in love with a property, it helps to understand the true cost of owning it.
1. Start With the Full Monthly Housing Payment
When estimating affordability, don't stop at principal and interest.
A more realistic monthly housing budget may include:
- Mortgage principal
- Mortgage interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, if applicable
- HOA or condominium fees
- Flood insurance, if required
- Other property-specific assessments
For example, a home with a seemingly affordable mortgage payment can become considerably more expensive once taxes, insurance, and HOA fees are added.
The goal isn't simply to qualify for a loan—it’s to determine what payment comfortably fits your lifestyle.
2. Don't Forget Property Taxes
Property taxes can vary substantially depending on the location and property.
This becomes particularly important when comparing homes across different communities—or across Delaware, Pennsylvania, and Maryland.
Two homes with similar purchase prices may have very different annual property-tax obligations.
Before making an offer, buyers should understand:
- Current annual property taxes
- How the tax bill is calculated
- Whether exemptions may apply
- Whether reassessment could affect future taxes
- Any special assessments associated with the property
Your real estate professional and lender can help you identify the numbers that should be included in your affordability calculation.
3. Budget for Homeowners Insurance
Insurance is another expense that buyers sometimes overlook when calculating affordability.
Premiums can vary based on factors such as:
- Location
- Property value
- Age and condition of the home
- Roof and major systems
- Claims history
- Coverage levels
- Certain environmental or geographic risks
Depending on the property, you may also need additional coverage.
Get an insurance estimate before you finalize your budget—not after.
4. Create a Home Maintenance Fund
Renters generally call the landlord when something breaks.
Homeowners call the plumber.
A realistic budget should include money for routine maintenance and eventual repairs.
Potential expenses include:
- HVAC servicing or replacement
- Roof repairs
- Plumbing issues
- Appliance replacement
- Landscaping
- Pest control
- Exterior maintenance
- Electrical repairs
- Water heater replacement
You won't necessarily spend the same amount every month, but setting aside money consistently can prevent an unexpected repair from becoming a financial emergency.
A simple mindset:
Don't budget only for today's house. Budget for tomorrow's repairs.
5. Estimate Your Utilities
Utilities can vary dramatically from one home to another.
A larger home, older HVAC system, poor insulation, or different heating source can all affect monthly costs.
Ask about typical expenses for:
- Electricity
- Natural gas
- Water
- Sewer
- Trash
- Internet
- Other property-specific services
If you're considering an older or significantly larger home, investigate utility costs before deciding what you can comfortably afford.
6. Account for HOA Fees
If you're purchasing a property within an HOA, don't treat the monthly fee as an afterthought.
HOA fees can help cover services and amenities such as:
- Community maintenance
- Landscaping
- Common-area insurance
- Clubhouses
- Pools
- Fitness facilities
- Snow removal
- Certain exterior maintenance
But buyers should also investigate whether fees have recently increased or whether special assessments are anticipated.
The monthly HOA fee should be part of your affordability calculation from day one.
7. Budget for the Upfront Costs
Your down payment isn't necessarily the only significant amount you'll need at closing.
Depending on the transaction, buyers may need funds for:
- Closing costs
- Inspections
- Appraisal
- Prepaid taxes
- Insurance
- Loan-related expenses
- Escrow funding
- Moving expenses
- Immediate repairs or improvements
That's why buyers should avoid putting every available dollar into the down payment.
Homeownership should leave you with financial breathing room—not an empty bank account.
8. Leave Room for Lifestyle Expenses
A home may technically fit your budget while still making your lifestyle uncomfortable.
Consider your other financial commitments:
- Car payments
- Student loans
- Childcare
- Groceries
- Travel
- Retirement contributions
- Emergency savings
- Credit-card payments
- Entertainment
- Education expenses
Ask yourself:
After paying all my housing expenses, can I still live the life I want?
That's a much better question than simply asking, "What mortgage payment can I qualify for?"
9. Build an Emergency Reserve
Homeownership comes with uncertainty.
The water heater doesn't care that you just bought the house. The HVAC system doesn't check your bank balance before breaking down.
An emergency fund can help protect your finances when unexpected expenses appear.
Rather than planning your budget down to the last dollar, leave room for the unexpected.
Financial flexibility is part of affordability.
10. Compare Homes by Total Cost—not Just Price
When evaluating multiple properties, don't automatically assume the house with the lower listing price is the less expensive option.
Instead, compare the estimated annual cost of ownership.
Consider:
Purchase Price + Mortgage + Taxes + Insurance + HOA + Utilities + Maintenance + Other Property Costs
This approach can reveal important differences between otherwise similar homes.
For example, a lower-priced home with high property taxes, expensive insurance, substantial maintenance needs, and significant HOA fees may have a very different overall cost than a slightly more expensive home with lower ongoing expenses.
A Simple Homeownership Budget Framework
Before making an offer, consider creating a worksheet like this:
| Expense | Estimated Monthly Cost |
|---|---|
| Mortgage Principal & Interest | $_____ |
| Property Taxes | $_____ |
| Homeowners Insurance | $_____ |
| HOA Fees | $_____ |
| Utilities | $_____ |
| Maintenance Reserve | $_____ |
| Mortgage Insurance | $_____ |
| Other Property Costs | $_____ |
| Estimated Total | $_____ |
Then compare that number with your take-home household income and existing financial obligations.
The result gives you a much clearer picture of whether a property fits your overall financial life.
The Bottom Line
Buying a home isn't just about getting approved for a mortgage.
It's about creating a financial plan that allows you to enjoy your home without feeling financially trapped by it.
A realistic homeownership budget should account for the costs you know about—and leave room for the ones you don't.
Before you start touring homes, talk with your lender and real estate professional about the full cost of ownership. Understanding the numbers early can help you shop more confidently, compare properties more intelligently, and avoid surprises later.
Ready to Start Looking at Homes?
At Sarpey Properties Group, we believe buyers deserve more than a list of properties. They deserve guidance that helps them understand the bigger financial picture behind the purchase.
Whether you're buying your first home, moving up, downsizing, or relocating within Delaware, Pennsylvania, or Maryland, we're here to help you evaluate the property—not just the price tag.
Let's talk about your homeownership goals and build a buying strategy around them.
Melvin & Dorothy Sarpey
Serving DE, PA, & MD
📞 Melvin: 302-312-6042
📞 Dorothy: 302-345-6122
📞 Office: 302-504-6147
🌐 www.sarpeypropertiesgroup.com
📱 Instagram/Facebook: @sarpeyrealty
Categories
- All Blogs (34)
- 2026 Housing Market (2)
- Buyer Resources (9)
- buyer strategy (2)
- Buyer tips (3)
- buying power (2)
- buying power, (1)
- Buying Tips (1)
- Client success stories (2)
- delaware home (1)
- Delaware Real Estate (21)
- energy efficiency (1)
- First time home buyer (8)
- home affordability (2)
- Home buyer (9)
- Home buying (17)
- home buying and selling (18)
- home buying tips (6)
- home financing (3)
- home inspections (2)
- home owner tips (2)
- home ownership (3)
- home sellers (1)
- home selling (9)
- home selling tips (8)
- home staging (2)
- home valuation (4)
- Homeownership (8)
- Homeownership Buyer Education (1)
- house (6)
- house buying guide (5)
- house hunting (6)
- housing market forecast (2)
- housing market trend (4)
- interest (4)
- interested rates (3)
- Lifestyle & Community Guides (1)
- Location & Lifestyle (1)
- market (7)
- market, (1)
- maryland home (2)
- Maryland Real Estate (23)
- maryland realtor (1)
- mortgage (4)
- mortgage and financing (5)
- mortgage approval (2)
- mortgage loans (1)
- open house tips (2)
- pennsylvania home (2)
- Pennsylvania Real Estate (22)
- property (1)
- Real Estate Advice (16)
- Real Estate Market Insights (8)
- real estate market trends (2)
- real estate marketing (5)
- real estate negotiation (3)
- real estate professionals (6)
- real estate selling tips (3)
- Real estate tips (12)
- Real estate, (12)
- Relocation & Moving (1)
- residential real estate (3)
- Sarpey (8)
- Sarpey Properties Group (9)
- seller resources (6)
- seller strategies (2)
- seller strategy (1)
- tax (3)
- Tri-State Real Estate (1)
- wealth building (2)
Recent Posts

"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "